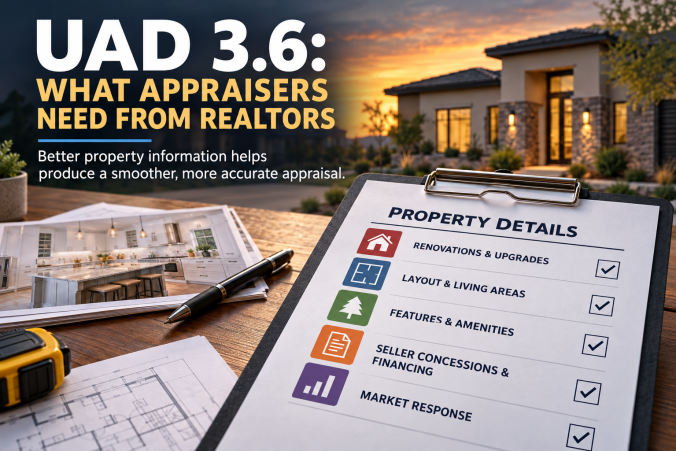
Beginning November 2, 2026, all new appraisal reports submitted to the Uniform Collateral Data Portal (UCDP) must use UAD 3.6.
Lenders can already use UAD 3.6, and Fannie Mae has said agents and appraisers should expect lenders to request the new format as the mandate approaches.
So, while November 2 is the official deadline, Realtors should start preparing now.

UAD 3.6 isn’t simply a new-looking appraisal form. Fannie Mae and Freddie Mac have redesigned how they collect and report property and market information. The new system uses a larger, more structured dataset and a dynamic appraisal report rather than relying as heavily on free-form commentary.
In practical terms, appraisers need more precise information about properties and transactions.
That makes the quality of information entered into MLS increasingly important—not only for the home you’re selling today, but also when that property becomes a comparable sale for another appraisal months or years from now.
Descriptions like“beautifully updated throughout” are becoming less useful from an appraisal standpoint. Facts, dates, and documentation are much more valuable.
1. Be Specific About Renovations and Updates
Instead of simply stating that a property has been remodeled, document what was done and approximately when it was completed.
For example:
Less useful:
“Beautifully updated kitchen.”

When possible, provide approximate ages or replacement dates for major components such as the roof, HVAC system, electrical, plumbing, windows, flooring, and other significant improvements.
Much more useful:
“Kitchen fully remodeled in 2022 with new cabinets, quartz countertops, appliances and flooring.”
The objective isn’t to make the MLS description sound technical. It’s to create a reliable record of the property’s condition and improvements that an appraiser can understand and potentially verify.
2. Provide Better Information About the Home’s Layout
UAD 3.6 places greater emphasis on detailed property characteristics, so agents should become accustomed to documenting the home’s layout more precisely.

Include bedrooms, full and half bathrooms, and finished versus unfinished areas by level whenever possible.
Also identify ADUs, additions, converted garages, finished basements, and other converted spaces. If a space was originally built for one purpose and is now being used for another, that information can be helpful. If you know whether the work was permitted, document that as well.
Fannie Mae has also published specific UAD 3.6 guidance on ANSI reporting and area breakdowns, reflecting the greater structure of the new appraisal reporting process.
3. Document Features That May Not Be Obvious
Think beyond bedrooms, bathrooms, and square footage.
Does the property have a detached garage, workshop, pool, spa, deck, outdoor kitchen,n or other significant amenity? Is there an ADU or guest quarters with a separate entrance, kitchen, bathroom, or utilities?
Solar deserves particular attention. If a solar system is present, indicate whether it is owned, financed, leased, or subject to another agreement, when known.
These details can help an appraiser understand how a property differs from competing homes.
4. Seller Concessions and Financing Matter
The final sales price doesn’t always tell the entire story.
If the seller provided concessions, document the total amount and purpose whenever possible. For example, was the money used for closing costs, a temporary or permanent interest-rate buydown, repairs, HOA expenses, es or something else?
Financing information can also provide useful context, including whether the transaction involved conventional, FHA, VA, or other financing.

Why does this matter?
Consider two homes that both sell for $500,000. One sells without concessions, while the other includes a substantial seller credit toward the buyer’s financing costs. Those transactions may provide different information to an appraiser analyzing the market.
5. Preserve the Story of the Sale
Agents should also document how the market responded to the listing.
Useful information can include the original list price, final list price, days on market, significant price changes, and whether the property received multiple offers.
If unusual circumstances surrounded the transaction—such as an estate sale, relocation, a non-arm’s-length transaction, or significant personal property included with the sale—those details may also provide important context.
The objective isn’t to influence the appraiser’s conclusion. It’s to give the appraiser accurate information about what actually happened.

6. For Current Listings, Keep the Documentation
When you have a property under contract, consider keeping an appraisal-ready package containing the complete purchase contract and addenda, documentation of seller concessions, builder upgrade or option sheets, solar agreements, and plans or permits for significant construction, additions, or conversions.
The appraiser may not need everything you’ve collected. But having it available is much easier than trying to reconstruct the property's history later.
And that brings us to what may be the most important reason Realtors should pay attention to UAD 3.6.
Once your transaction closes, your MLS listing doesn’t stop being important.
That property may be used as a comparable sale in appraisals throughout the neighborhood for years.

Imagine an appraiser using your listing 18 months from now. The MLS says only “gorgeous remodeled home!” The appraiser may have no idea what was remodeled, when it was completed, whether the HVAC was replaced, whether a converted area was permitted, or whether the transaction included substantial concessions.
Someone may have to track down the listing agent to find out.
Now imagine the original listing already includes specific renovation dates, property characteristics, transaction information, and detailed remarks. The historical record becomes much more useful.
Better MLS information today can mean fewer verification calls later—and potentially fewer appraisal questions, delays, and revision requests on future transactions.
The November 2 mandate applies to new appraisal reports submitted to UCDP, but the transition is already underway. UAD 3.6 has been available for broad production since January 26, 2026, and Fannie Mae and Freddie Mac are encouraging the mortgage industry to transition before the deadline.
So real estate agents have little reason to wait.

Start creating listings with the future appraiser in mind. Be specific about improvements. Document dates. Describe the layout accurately. Record concessions and financing details. Preserve information about how the market responded to the property.
Great marketing still matters. Beautiful photographs and compelling descriptions still help sell homes.
But under the new appraisal environment, good data matters, too. Here are the specific links that Fannie and Freddie provide:
The agents who build better information into their listings today aren’t just helping the current transaction. They’re creating a better historical record for every transaction in which that property may eventually be used as a comparable sale.
Feel free to contact me anytime to continue the dialogue.
Mike Nelson, Efficient Lending, Inc
720.419.3016 | mike@efficientlending.net | @mike_lending
NMLS: 1876539 | NMLS: 1314188
Licensed in Colorado, Texas, and Florida
